Build it
Build it
Development finance
Ground-up, conversion and part-built schemes, from site purchase to exit.
See all →
Development finance
Which cap binds, loan to cost or loan to GDV, and the real day-one equity.
Build to Rent development
Underwritten on stabilised yield and DSCR, not sales rate.
Mezzanine and stretched senior
The gap between senior LTC and what you can fund, and the true blended cost.
Heavy refurbishment and conversion
Where refurbishment stops being a bridge: structure, change of use, drawdowns.
Part-built and rescue finance
Valuing an unfinished asset when the contractor has gone.
Bridge it
Bridge it
Bridging finance
Short-term debt where the deadline, the asset or the exit will not wait.
See all →
Purchase bridge
Completing before the money is in place: chain breaks, tight deadlines, unmortgageable stock.
Development exit finance
Off development debt at a lower rate, to buy sales time and release equity.
Auction finance
A 28-day clock, and what must be in place before the hammer falls.
Pre-planning and planning gain
Lending against current value with planning upside.
Below market value purchase
Day-one lending against open market value rather than price.
Second charge and capital raising
Raising against existing assets, and first-charge consent.
Light refurbishment finance
Bridge plus refurb tranche, and where the development boundary sits.
Also structuredBridge to let and refinance
Hold it
Hold it
Mortgages and term finance
Long-term debt against income, once the asset is built, let or trading.
See all →
Buy to let mortgages
ICR stress testing, limited company against personal, portfolio rules.
HMO mortgages
A higher cover test, licensing, and the two valuations a lender takes the lower of.
Commercial term, investment
Tenant covenant and lease term, and why DSCR sets the loan.
Commercial term, owner-occupier
Trading accounts and EBITDA rather than rent roll.
Portfolio refinance
Cross-collateralisation, and one facility against individual loans.
Stabilisation and term refinance
The income test replacing the GDV test, and the letting void before term debt engages.
Co-living and PBSA
An operational asset valued on income, and the operator covenant.
Run it
Run it
Business finance
Funding the business behind the property, secured on the ledger, the equipment or the covenant.
See all →
How we work
Case studies
Articles
Tools
Development finance calculator
Size the facility against site cost, build cost and GDV.
Development exit calculator
Refinance the development facility and release equity at PC.
Bridging finance calculator
What a bridge costs, and what actually clears on day one.
Refurbishment finance calculator
Fund the purchase and 100% of the works, with interest rolled to exit.
BTL rental cover calculator
The rent a buy to let must achieve to clear a lender's cover test.
Commercial mortgage calculator
What a commercial property's income will support, and what it costs.
About
Enquire now
Build it › Heavy refurbishment and conversion
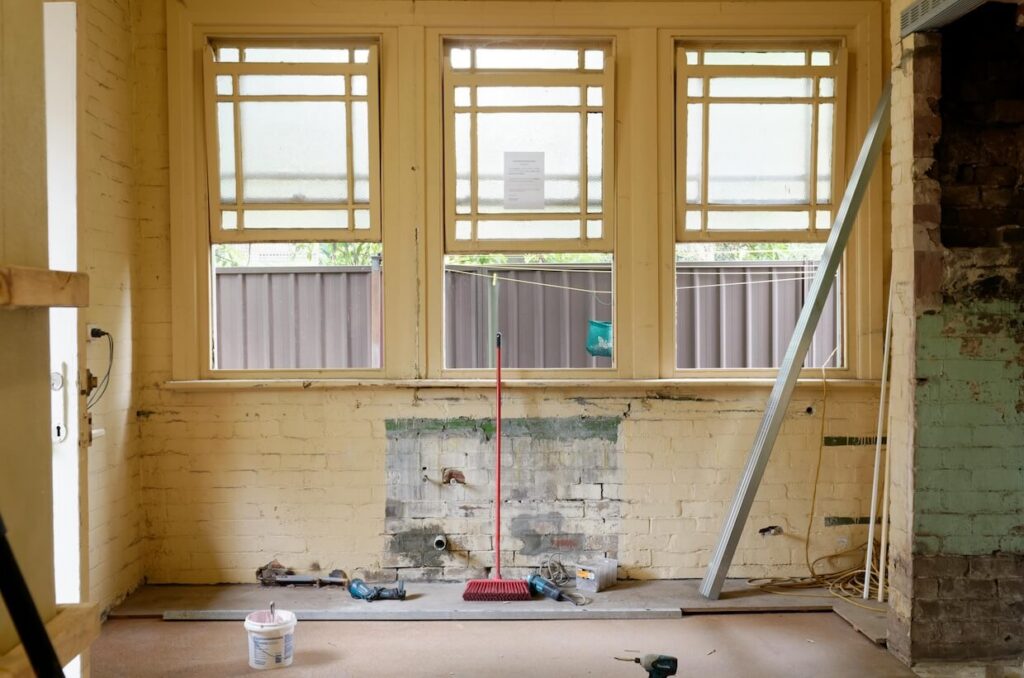
There is a line between light and heavy refurbishment, and it moves the lender, the price and the process. Works costing more than around 50% of the property's current value, anything structural, or a change of use take a scheme into heavy refurbishment: staged drawdowns, a monitoring surveyor, and a loan sized on the finished value as well as today's. Further on there is a second line. Creating new units, or works approaching 60% of gross development value, is development finance, whatever the deal is called on the enquiry.
The valuation works differently too. A property worth £300,000 today that will be worth £550,000 after a structural conversion is not a 300 or a 550 case; it is both, and the facility is sized against each at different stages. Lending purely on current value understates the scheme, and lending purely on end value ignores where you are standing today.
What sinks these applications is almost never the asset. It is the schedule of works. 'Full refurb, £80,000' is not a schedule, and a lender that cannot see line by line what is being done, by whom and when will either decline or price for the uncertainty you have handed them.
Three ceilings applied together, and the tightest sets the advance.
A schedule of works a lender can underwrite
Line by line, with a contingency of 10% to 15% of build cost stated explicitly rather than assumed. Above roughly £500,000 of build cost expect a quantity surveyor's cost review, so it is worth writing the schedule as though one is coming.
Both values, at the right moments
Current value sets the day one advance and end value sets the total facility. We make sure the valuation is instructed on the right basis, because a report addressing only one of them will not support the structure.
Drawdowns and the monitoring surveyor
Works are funded in arrears against inspection. Monitoring surveyor fees are yours to pay, so visit frequency is a cost line and worth negotiating rather than accepting.
Planning and change of use resolved first
A conversion without its consent in place, or with conditions still to discharge, is a different risk and a different price. Knowing which conditions are outstanding before you apply is the cheapest work in the process.
Which lenders play here
Specialist bridging lenders with a development desk, and development lenders who will take a standing building. Which of the two you want depends on how much of the value is created by the works: the more structural the scheme, the further towards development lending it belongs.
Both
Current and end value assessed
50%
Works to current value, heavy above
10-15%
Contingency on build cost
£500k
Build cost, QS review from
Indicative, and not an offer. What a lender will actually do depends on the scheme, the borrower and a full valuation.
What to have ready
Bring these and we can tell you where you stand.
Each one is something a lender will ask for. Having it early is the difference between a fast answer and a slow one.
✓A schedule of works, line by line, with a stated contingency
✓Current valuation or purchase price, and your view of end value with evidence
✓Planning consent and change of use where relevant, and outstanding conditions
✓The contractor, their track record, and whether the price is fixed
✓Programme, with the drawdown profile the works actually need
✓Your exit: sale, refinance to term, or letting, and the evidence for it
Related case study
£5m GDV North Wales Development + North London Refurbishment
Related
Worth reading on this
Article
What is Heavy Refurbishment Finance and When Does it Become More Than a Refurb?
Article
Mezzanine Finance: Bridging the Equity Gap on Your Next Development
Article
Free Development Finance Calculator & Loan Appraisal Guide
Next
Related in this pillar.
Common questions
The questions this product raises.
What is the difference between light and heavy refurbishment finance?
Light refurbishment is a bridge with works attached. Heavy refurbishment is underwritten as development. Anything structural, any change of use, or works costing more than around 50% of the property's current value moves a scheme into the heavy category, whatever it is called on the enquiry. That changes the lender, the price and the process.
Is a heavy refurbishment lent on today's value or the finished value?
Both, at different stages. Current value sets the day one advance, and the finished value sets the total facility. A property worth £300,000 today and £550,000 after conversion is both a 300 case and a 550 case, so the valuation has to address both values or it will not support the structure.
What does a lender want to see in the schedule of works?
Line by line: what is being done, by whom and when, with a contingency of 10 to 15% of build cost stated rather than assumed. “Full refurb, £80,000” is not a schedule. Above roughly £500,000 of build cost, expect a quantity surveyor to review it, so write it as though one is coming.
Do I need planning in place before I apply?
For a conversion, ideally yes, with conditions discharged or a clear plan for them. A scheme without its consent, or with conditions outstanding, is a different risk and a different price. Knowing which conditions are still open before you apply is the cheapest work in the whole process.
Bring us the detail.
Send what you have. We will tell you what is fundable and what needs work before anyone approaches a lender.
Specialist property finance for developers who want the numbers to survive underwriting.
020 4572 4266LinkedIn
Fundingwise Limited is not authorised or regulated by the Financial Conduct Authority, and arranges unregulated finance only. That means lending secured against commercial property, or against residential property that is not, and will not be, occupied by the borrower or an immediate family member as a main residence. We do not advise on or arrange regulated mortgage contracts or regulated bridging loans. Because this finance is unregulated, FCA conduct rules and access to the Financial Ombudsman Service do not apply. Fundingwise Limited is registered in England and Wales, company number 13750788.