Build it
Build it
Development finance
Ground-up, conversion and part-built schemes, from site purchase to exit.
See all →
Development finance
Which cap binds, loan to cost or loan to GDV, and the real day-one equity.
Build to Rent development
Underwritten on stabilised yield and DSCR, not sales rate.
Mezzanine and stretched senior
The gap between senior LTC and what you can fund, and the true blended cost.
Heavy refurbishment and conversion
Where refurbishment stops being a bridge: structure, change of use, drawdowns.
Part-built and rescue finance
Valuing an unfinished asset when the contractor has gone.
Bridge it
Bridge it
Bridging finance
Short-term debt where the deadline, the asset or the exit will not wait.
See all →
Purchase bridge
Completing before the money is in place: chain breaks, tight deadlines, unmortgageable stock.
Development exit finance
Off development debt at a lower rate, to buy sales time and release equity.
Auction finance
A 28-day clock, and what must be in place before the hammer falls.
Pre-planning and planning gain
Lending against current value with planning upside.
Below market value purchase
Day-one lending against open market value rather than price.
Second charge and capital raising
Raising against existing assets, and first-charge consent.
Light refurbishment finance
Bridge plus refurb tranche, and where the development boundary sits.
Also structuredBridge to let and refinance
Hold it
Hold it
Mortgages and term finance
Long-term debt against income, once the asset is built, let or trading.
See all →
Buy to let mortgages
ICR stress testing, limited company against personal, portfolio rules.
HMO mortgages
A higher cover test, licensing, and the two valuations a lender takes the lower of.
Commercial term, investment
Tenant covenant and lease term, and why DSCR sets the loan.
Commercial term, owner-occupier
Trading accounts and EBITDA rather than rent roll.
Portfolio refinance
Cross-collateralisation, and one facility against individual loans.
Stabilisation and term refinance
The income test replacing the GDV test, and the letting void before term debt engages.
Co-living and PBSA
An operational asset valued on income, and the operator covenant.
Run it
Run it
Business finance
Funding the business behind the property, secured on the ledger, the equipment or the covenant.
See all →
How we work
Case studies
Articles
Tools
Development finance calculator
Size the facility against site cost, build cost and GDV.
Development exit calculator
Refinance the development facility and release equity at PC.
Bridging finance calculator
What a bridge costs, and what actually clears on day one.
Refurbishment finance calculator
Fund the purchase and 100% of the works, with interest rolled to exit.
BTL rental cover calculator
The rent a buy to let must achieve to clear a lender's cover test.
Commercial mortgage calculator
What a commercial property's income will support, and what it costs.
About
Enquire now
Bridge it › Development exit finance
A development facility is priced for the risk of building. Once the scheme is built that risk has gone, but the facility has not: it is still charging development rates on a finished asset, and it still has an expiry date that was set before a brick was laid.
That expiry is the real problem. A sales period compressed into the last weeks of a facility is a sales period run at the buyer's advantage, and every agent involved knows it. Discounting a single unit to hit a redemption date usually costs more than a year of exit finance would have.
Development exit finance replaces the development loan with a cheaper facility priced against a completed asset. It buys a longer sales window, and where the scheme has performed it can release equity at the same time, which is the capital that funds the next site rather than sitting in this one.
See what an exit facility releases against your current value and outstanding balance.
Refinance before you are forced to
The strongest terms are available while the existing facility still has time on it. An exit arranged with six weeks left is a different conversation from one arranged with six months, and it is priced accordingly.
Sized on current value, not GDV
Typically up to 75% of current value, and up to 80% where units are sold subject to contract, on terms of up to 24 months. A part-sold scheme changes the figures, so the timing of the valuation is part of the structure.
Equity release where the scheme has performed
If the finished value beats the appraisal, the difference is releasable. That is deposit for the next site, and it is available at the point most developers assume their capital is locked up.
Priced against a finished asset
A completed scheme with no build risk prices materially below development debt. The saving compounds across the sales period, which is exactly the period that tends to run longer than planned.
Which lenders play here
Bridging lenders across the market compete here, because a finished, valued, insurable asset is the most straightforward security a short-term lender sees. The spread between the best and worst quote on the same scheme is wide, which is the whole argument for going out to more than one.
75%
Standard max LTV
80%
Where units are sold STC
24m
Max term
Before expiry
When to refinance
Indicative, and not an offer. What a lender will actually do depends on the scheme, the borrower and a full valuation.
What to have ready
Bring these and we can tell you where you stand.
Each one is something a lender will ask for. Having it early is the difference between a fast answer and a slow one.
✓Practical completion certificate, or a realistic date for it
✓The existing facility: balance, expiry date, and any exit fee already accrued
✓Current valuation, or the last one and what has changed since
✓Sales evidence: reservations, exchanges, completions and the agent's view
✓Building control sign-off, warranties and the health and safety file
✓Your intended exit, whether that is sales, refinance to term, or both
Deals we have funded
What it looked like when the numbers were real.
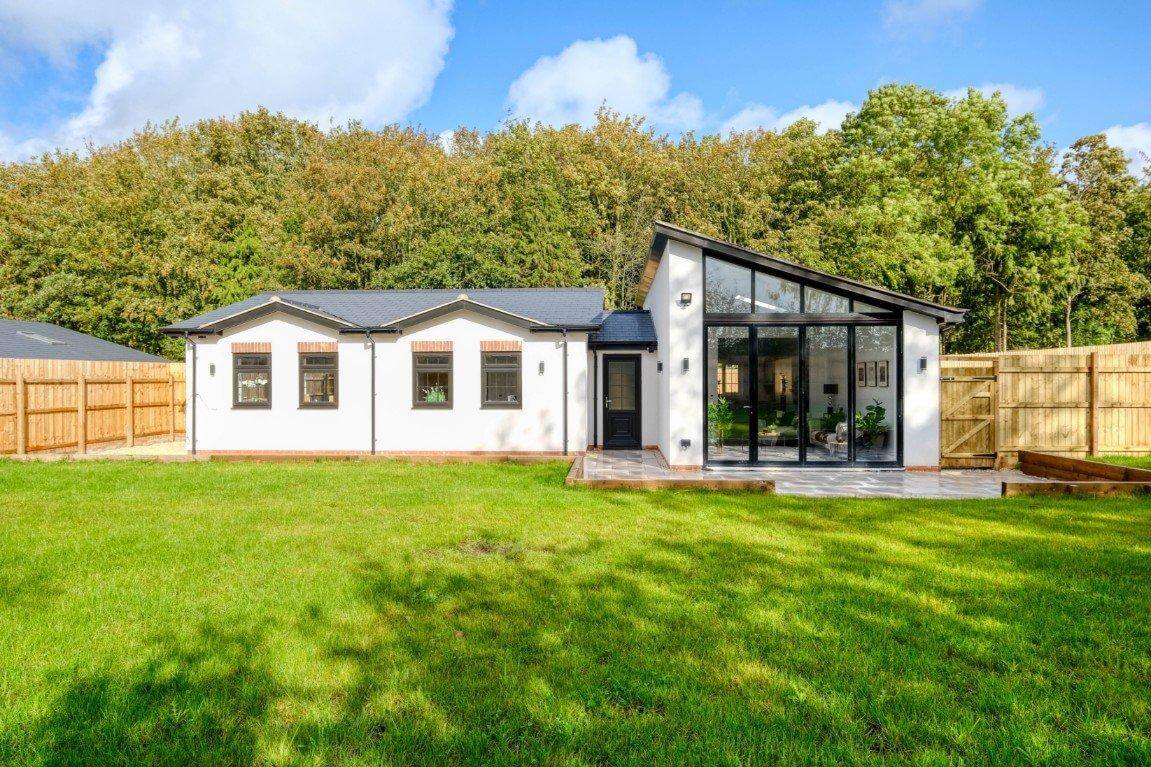
£1.7m at 75% LTV, Woodland Mews
Stepped rates and a four week completion, releasing capital for the next site.
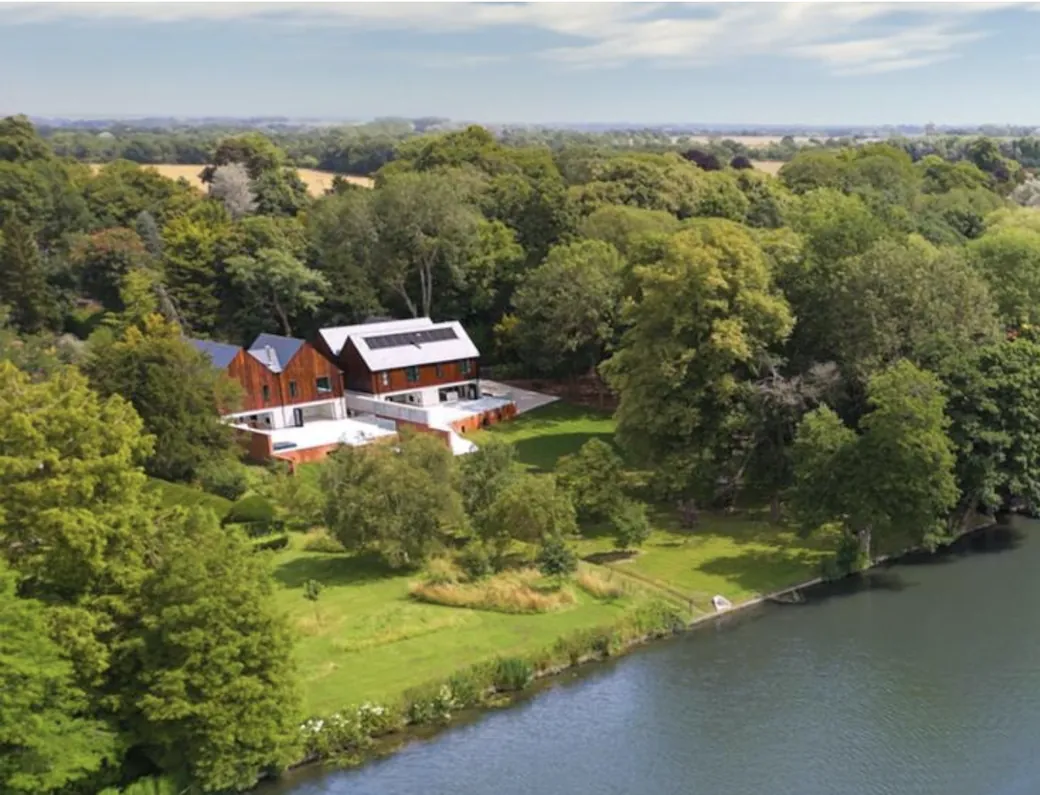
£3.1m riverside homes, Oxfordshire
Two high specification homes against a combined £7m GDV.
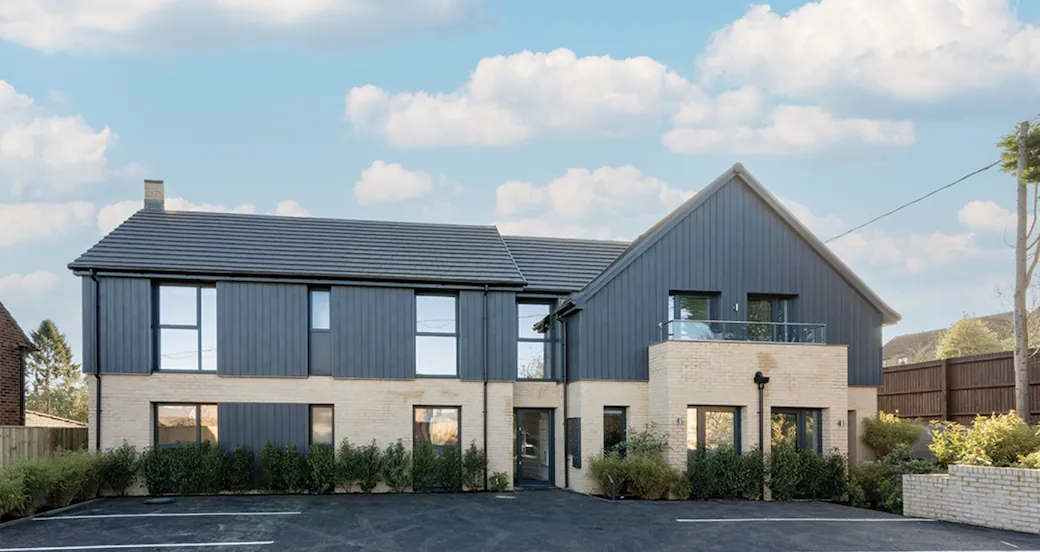
£1.3m Oxford apartments
Seven apartments, a tight lender deadline, and extension fees avoided.
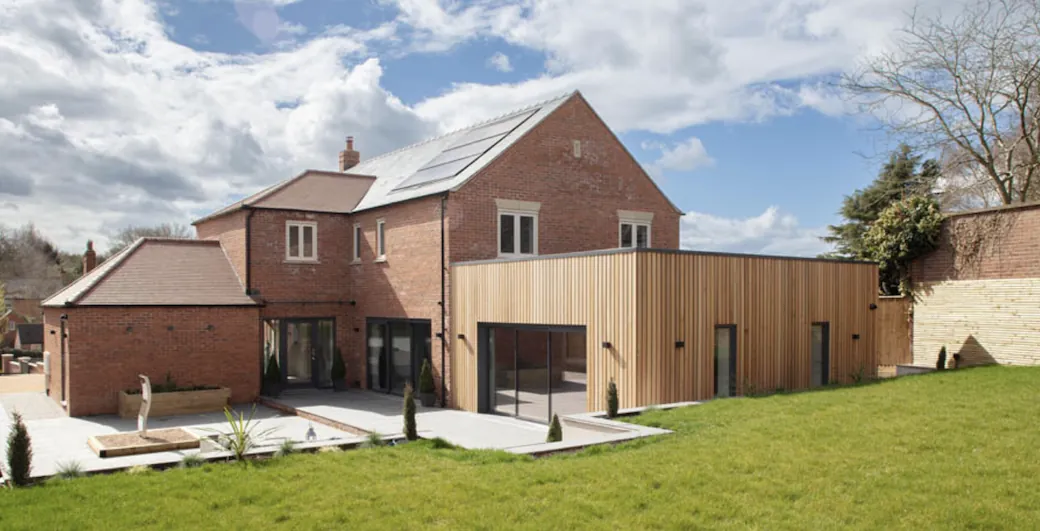
£865k with a month left, East Midlands
Planning conditions still open and the facility about to expire. Completed before the deadline.
£11m across two Kent schemes
Two development facilities redeemed at once, lent against GDV before practical completion.
Related
Worth reading on this
Article
Finish and Exit Finance: What If Your Loan Runs Out Before the Build Is Done?
Article
Development Exit Finance: What It Is and When You Need It
Case study
£865k Development Exit Bridge for Luxury 5-Bed Home, East Midlands
Next
Related in this pillar.
Common questions
The questions this product raises.
What is development exit finance?
A loan that replaces your development facility once the scheme is built. Development debt is priced for build risk. Once the building is finished that risk has gone, so a facility priced against a completed asset costs less. It buys a longer sales window, and where the scheme has performed it can release equity for the next site.
My development facility is about to expire. Can exit finance help?
Yes, but the earlier the better. The strongest terms are available while the existing facility still has time on it. An exit arranged with six weeks left is a different conversation from one arranged with six months. Discounting a unit to hit a redemption date usually costs more than a year of exit finance would have.
How much will a development exit loan advance?
Typically up to 75% of current value, and up to 80% where units are sold subject to contract, on terms of up to 24 months. We completed Woodland Mews at 75% of value. A part-sold scheme changes the figures, so when the valuation is done is part of the structure.
Can development exit finance release equity?
Yes, where the finished value beats the appraisal. The difference can be released as cash at completion, which is often the deposit for the next site, at the point most developers assume their capital is locked up.
Bring us the detail.
Send what you have. We will tell you what is fundable and what needs work before anyone approaches a lender.
Specialist property finance for developers who want the numbers to survive underwriting.
020 4572 4266LinkedIn
Fundingwise Limited is not authorised or regulated by the Financial Conduct Authority, and arranges unregulated finance only. That means lending secured against commercial property, or against residential property that is not, and will not be, occupied by the borrower or an immediate family member as a main residence. We do not advise on or arrange regulated mortgage contracts or regulated bridging loans. Because this finance is unregulated, FCA conduct rules and access to the Financial Ombudsman Service do not apply. Fundingwise Limited is registered in England and Wales, company number 13750788.